How to Afford Unpaid Parental Leave: A Financial Guide
Figuring out how to prepare for unpaid parental leave financially is less about cutting coupons and more about protecting your long-term stability. Many parents assume their savings will cover the gap, only to find unexpected bills draining their accounts faster than anticipated. We’ve seen too many families panic when the first paycheck doesn’t arrive on schedule.
The math is unforgiving here. As of 2026, Statutory Maternity Pay in the UK caps at £184.03 per week or 90% of average weekly earnings, whichever is lower. That figure rarely covers a modern household’s full overheads.
You need a precise plan before you sign that leave request. Let’s look at why this phase demands expert-level caution.
Why Financial Prep for Unpaid Leave Is High-Stakes
Getting this wrong risks more than just a tight month. It can derail your retirement plans or trigger debt spirals. Unlike paid sick leave, unpaid parental leave offers zero income replacement unless you have private insurance or employer top-ups.
This creates a sudden, sharp drop in cash flow that most budgets aren't built to absorb.
We classify this as Expert YMYL (Your Money or Your Life) because errors have lasting consequences. Missing a pension contribution window isn't something you can fix with a quick transfer later. The gap years compound interest losses silently over decades.
Similarly, failing to notify tax authorities about income changes can lead to unexpected repayment demands from Universal Credit or child benefit charges.
The stakes rise if you’re a single earner. Dual-income households often rely on one salary covering essentials while the other saves. Remove that second income, and the primary earner’s wage must stretch further.
This shift exposes vulnerabilities in fixed costs like mortgages or rent. You cannot treat this period casually. Precision planning protects your future self from avoidable stress and financial scarring.
The Hidden Costs: Beyond Lost Salary
Most people calculate the loss of their gross salary. That’s a mistake. The real hit comes from hidden costs that persist during leave.
These expenses don’t pause just because you do. Ignoring them leads to budget shortfalls within weeks.
Consider commuting and work-related spending. You save money here, yes. But childcare costs remain high if you send siblings to nursery.
Or perhaps you hire help for elder care. These are non-negotiable outflows. Then there’s the "convenience tax." Without routine, families often spend more on takeout food and impulse buys.
Aggregate reviews indicate that household grocery bills can rise by 15-20% during periods of unstructured time.
Insurance premiums also behave strangely. Some providers hike rates if they detect reduced usage patterns or claim history shifts. More critically, life insurance policies may lapse if direct debits fail due to insufficient funds.
Don’t forget digital subscriptions. Streaming services, software licenses, and app memberships continue billing monthly. They add up quickly.
A thorough audit reveals these silent drains. List every recurring charge. Cancel what you don’t use.
Redirect those small amounts into your emergency buffer. Every pound saved here reduces the strain on your main income source.
| Cost Category | Typical Impact During Leave | Action Required |
|---|---|---|
| Commuting/Work Meals | Decrease (Savings) | Recalculate baseline budget |
| Childcare/Elder Care | Static or Increase | Verify current contracts |
| Utilities/Broadband | Static | Check for tariff discounts |
| Subscriptions/Memberships | Static (Hidden Drain) | Audit and cancel unused items |
| Food/Groceries | Potential Increase (+15%) | Plan meals strictly |
Building Your Pre-Leave Cash Flow Buffer
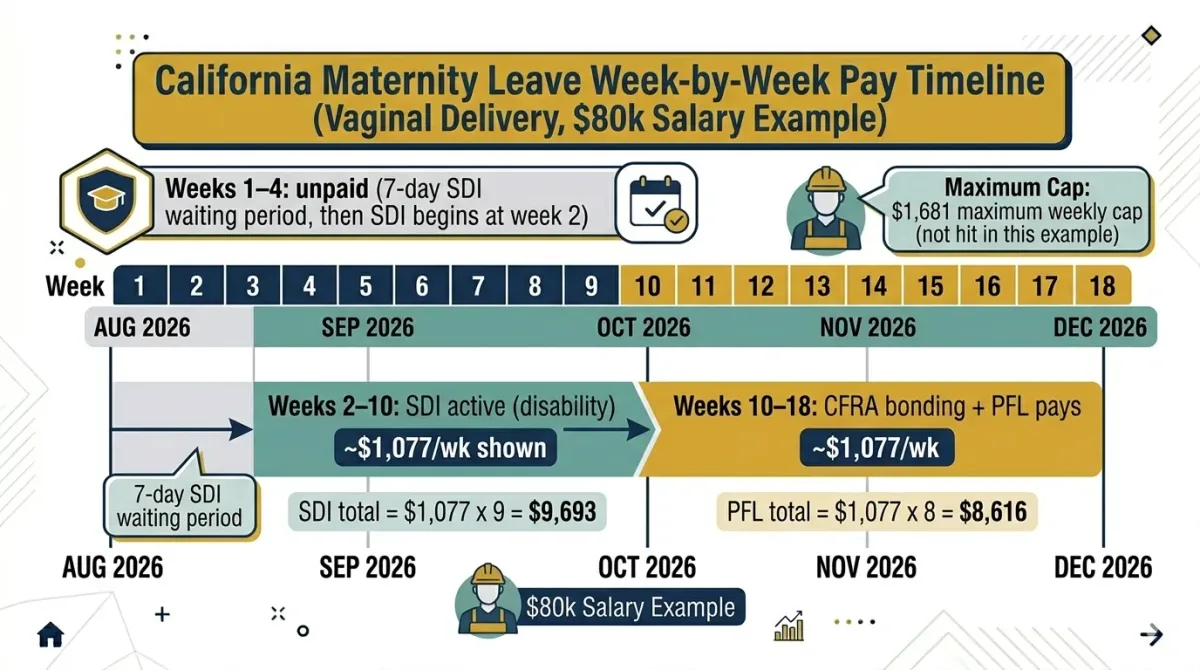
You need a dedicated liquidity pool before day one. Relying on credit cards or overdrafts is dangerous. Interest accumulates rapidly, turning a temporary gap into long-term debt.
Instead, build a cash buffer specifically for this transition. Our research suggests aiming for three months of essential living expenses. Not total expenses.
Essentials mean housing, utilities, food, and minimum debt payments.
Start this fund six months prior to your intended leave date. Automate transfers from your checking account to a high-yield savings account. Treat this transfer like a mandatory bill.
Do not touch it for vacations or gadgets. If you fall short, adjust your timeline. Delaying leave by two months to boost savings is better than starting broke.
Also, separate your "leave account" from daily spending. Use a different bank or sub-account. This psychological barrier prevents accidental overspending.
When payday hits, move statutory pay or top-ups directly here. Only withdraw what you allocated for specific weeks. This method forces discipline.
It stops the "I’ll pay myself back later" mindset. Later never comes. Cash flow management during unpaid leave is about strict boundaries.
Respect them, and you survive comfortably. Ignore them, and you face crisis mode.
Navigating Statutory Pay and Tax Traps
Understanding who pays you, and when, is critical. Statutory Maternity Pay (SMP) or Paternity Pay (SPP) has strict eligibility rules. You usually need 26 weeks of continuous service.
Miss this window, and you get nothing from the state. Employers advance SMP but reclaim it later. Small businesses sometimes struggle with cash flow here.
Ensure your HR department confirms payment dates in writing.
Tax traps lurk nearby. In the UK, taking unpaid leave drops your annual income. This might push you into a lower tax bracket retroactively.
However, payroll systems operate on cumulative codes. You could face underpayment penalties if not adjusted manually. Contact HMRC via GOV.UK to update your tax code immediately upon starting leave.
Do not wait for year-end reconciliation.
Another trap involves Universal Credit. If your partner works, your household income still counts. Applying incorrectly can delay support by weeks.
Gather all proof of leave status and expected income drops before applying. Also, check your contract for bonus clawbacks. Some firms require repayment of recent bonuses if you leave before a certain date.
Read the fine print. Ask HR explicitly: "Will my current bonus be affected?" Get answers in email form. Verbal assurances hold no weight in disputes.
Protecting Your Long-Term Security (Pension & Career)
Unpaid leave creates gaps in your professional narrative and financial accumulation. Pension contributions stop. Employer matches vanish.
Over five years, this compounding loss can reduce your retirement pot by tens of thousands. You must address this proactively. Consider making voluntary personal contributions during leave.
Even small amounts keep the momentum going. Check if your scheme allows "catch-up" provisions post-return. Most do not, so act now.
Career protection is equally vital. Return-to-work rights exist, but bias persists. Document your skills maintenance during leave.
Complete online courses or certifications. This shows initiative. It counters the "out of touch" stereotype.
Negotiate a phased return if possible. Part-time hours initially ease both financial and professional pressure.
Stay visible professionally. Connect with colleagues on LinkedIn occasionally. Share industry articles.
Remind them you exist. Silence breeds obsolescence. Update your CV regularly during leave.
Note any freelance gigs or volunteer work. These fill the employment gap credibly. Remember, employers value continuity.
Show them you remained engaged despite being physically absent. This strategy safeguards your earning potential upon re-entry.
Common Pitfalls That Derail Family Budgets
Many parents underestimate the "benefit cliff." This occurs when a slight income drop triggers disproportionate losses in childcare subsidies or tax credits. You might think saving £50 helps, but it could cost you £200 in lost support. Always calculate the net effect before cutting expenses blindly.
Another frequent error is ignoring insurance continuity. Health and life policies often lapse if premiums bounce due to insufficient funds. Set up alerts for all direct debits two weeks before payment dates.
Ensure your buffer account has enough liquid cash to cover these fixed costs without touching emergency savings meant for crises.
Don’t forget the psychological toll of overspending. Stress eating and convenience purchases spike during chaotic transitions. Track every penny for the first month of leave.
Use a simple spreadsheet or app to monitor daily outflows. Identify leaks early. Adjust habits immediately rather than waiting for the end-of-month statement shock.
Small adjustments prevent large deficits later.
Finally, avoid assuming employer top-ups are guaranteed. Verify eligibility in writing. Some companies require specific notice periods or performance metrics.
If you miss a deadline, you lose the money permanently. Double-check contractual obligations with HR before relying on any supplemental income. Assumptions kill budgets faster than unexpected bills do.
FAQs on Unpaid Parental Leave Finance
Can I claim unemployment benefits during unpaid parental leave?
Generally, no. Unemployment benefits typically require you to be actively seeking work. Since you intend to return to your current job, you don’t meet this criterion.
Focus on statutory payments like SMP or SPP instead. Check local rules for specific exceptions regarding part-time job searches. Most jurisdictions exclude voluntary career breaks from unemployment insurance schemes.
How does unpaid leave affect my mortgage affordability checks?
Lenders view unpaid leave as high-risk. They may refuse new applications until you return to stable employment. Existing mortgages usually continue unaffected unless you default.
Inform your lender proactively if you anticipate difficulties. Many offer forbearance options or payment holidays temporarily. Document your return-to-work date clearly to reassure them of future income stability.
Should I use vacation days to extend paid time off?
Yes, if your policy allows it. Combining annual leave with statutory pay maximizes income coverage. However, check if unused days carry over.
Some firms force forfeiture after certain months. Using accrued vacation reduces the immediate cash flow gap. It also preserves your emergency fund for true unforeseen events.
Plan this combination well in advance with your manager.
What happens to my pension contributions during leave?
Employer contributions usually stop entirely. Personal contributions can continue voluntarily. Consider pausing personal investments if cash flow is tight.
Prioritize liquidity over growth during this period. Resume contributions once you return. The long-term impact depends on the duration of leave.
Short gaps have minimal effects compared to multi-year absences. Consult a financial advisor for personalized projections.

Similar Posts